


seqcomp is an R package for anytime-valid sequential
comparison of probabilistic forecasters, implementing the framework of
Choe and Ramdas (2024). Given two competing forecasters and a sequence
of binary or categorical outcomes, the package constructs confidence
sequences and e-processes for the running mean score difference that are
valid simultaneously at every point in time, without requiring a
pre-specified sample size or adjustment for repeated monitoring. For
three or more forecasters, seqcomp also implements
Sequential Model Confidence Sets (Arnold, Gavrilopoulos, Schulz and
Ziegel, 2026), which extend this guarantee to a running subset of models
that have not yet been shown to underperform.
The package provides:
All boundary computations (normal mixture, gamma-exponential mixture,
polynomial stitching) are implemented from scratch, with no dependency
on the confseq package.
Available on CRAN:
install.packages("seqcomp")The development version can be installed from GitHub:
# install.packages("pak")
pak::pak("alasgarliakbar/seqcomp")compare_forecasts() is the main entry point. It computes
pointwise scores, the running mean score difference, a confidence
sequence, and two one-sided e-processes in a single call.
library(seqcomp)

set.seed(1)
n <- 300
y <- rbinom(n, size = 1, prob = 0.55)

# Forecaster p has some signal; forecaster q always predicts 0.5
p <- ifelse(y == 1, 0.62, 0.38)
q <- rep(0.50, n)

out <- compare_forecasts(
  p            = p,
  q            = q,
  y            = y,
  scoring_rule = "brier"
)

tail(out[, c("t", "estimate", "lower", "upper", "e_pq", "e_qp")])
#>       t estimate      lower     upper    e_pq         e_qp
#> 295 295   0.1056 0.07758913 0.1336109 2681618 2.220446e-16
#> 296 296   0.1056 0.07768377 0.1335162 2824574 2.220446e-16
#> 297 297   0.1056 0.07777776 0.1334222 2975161 2.220446e-16
#> 298 298   0.1056 0.07787112 0.1333289 3133784 2.220446e-16
#> 299 299   0.1056 0.07796386 0.1332361 3300873 2.220446e-16
#> 300 300   0.1056 0.07805598 0.1331440 3476882 2.220446e-16
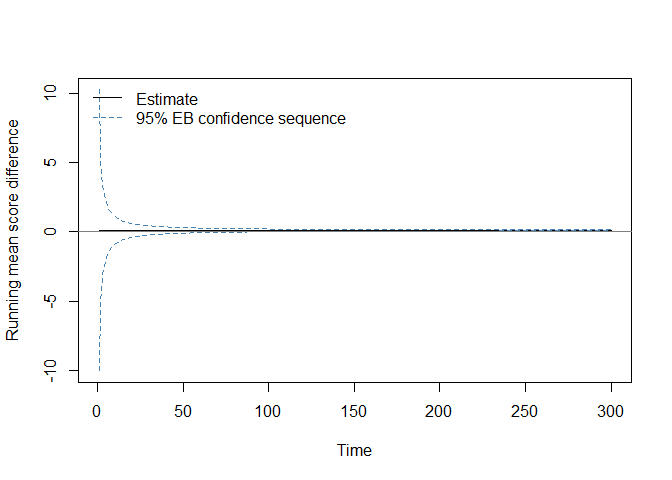
The column estimate is the running mean score difference
\(\hat{\Delta}_t =
\frac{1}{t}\sum_{i=1}^{t}(S(p_i,y_i)-S(q_i,y_i))\). Positive
values favour p; negative values favour q. The
columns lower and upper are the empirical
Bernstein confidence sequence bounds. The columns e_pq and
e_qp are the two one-sided e-process values; the two-sided
rejection threshold at level alpha = 0.05 is
2 / 0.05 = 40.
plot(
  out$t, out$estimate,
  type = "l",
  ylim = range(c(out$lower, out$upper, 0), finite = TRUE),
  xlab = "Time",
  ylab = "Running mean score difference"
)
lines(out$t, out$lower, lty = 2, col = "steelblue")
lines(out$t, out$upper, lty = 2, col = "steelblue")
abline(h = 0, col = "gray50")
legend(
  "topleft",
  legend = c("Estimate", "95% EB confidence sequence"),
  lty    = c(1, 2),
  col    = c("black", "steelblue"),
  bty    = "n"
)
Two scale conventions are used throughout, following Choe and Ramdas
(2024) exactly. Theorem 1 (Hoeffding CS) requires \(|\hat{\delta}_i| \leq c\), so
c = 1 is used for Brier or spherical score differences in
\([-1, 1]\). Theorems 2 and 3
(empirical Bernstein CS and e-process) require \(|\hat{\delta}_i| \leq c/2\), so
c = 2 is used for the same score differences.
compare_forecasts() applies these conventions
automatically. They differ from the Python comparecast
package, which applies the Theorem 2/3 convention throughout.
compare_forecasts() is a convenience wrapper. The
underlying functions can be called directly for finer control:
scores_p <- brier_score(p, y)
scores_q <- brier_score(q, y)

cs  <- cs_bernstein(scores_p, scores_q, alpha = 0.05, c = 2)
ep <- eprocess(scores_p, scores_q, alpha = 0.05, c = 2)For three or more candidate forecasters, use
smcs_compare(), which extends the same anytime-valid
guarantees to a Sequential Model Confidence Set (SMCS):
out <- smcs_compare(
  forecasts    = cbind(p1, p2, p3),
  outcomes     = y,
  scoring_rule = "brier"
)

tail(out$smcs_strong)
See the
SMCS vignette for the strong and weak notions of superiority, and
the closed-testing multiplicity correction. Or, access it locally via
vignette("smcs", package = "seqcomp").
smcs_strong()’s default betting fraction is the
conservative fixed rule \(\lambda_t =
1/(2c_t)\); adaptive alternatives
(lambda_betting_agrapa(),
lambda_betting_ons()) can substantially speed up rejection
under autocorrelated or abruptly shifting score differences, at some
cost in robustness elsewhere. See the
adaptive betting vignette for a worked comparison, or
vignette("adaptive_betting", package = "seqcomp")
locally.
The statistical methods in seqcomp are based on:
The package was developed as part of a bachelor’s thesis at the Vienna University of Economics and Business (WU Vienna).
If this package is used in published work, please cite the package itself and the following papers:
citation("seqcomp")Arnold, S., Gavrilopoulos, G., Schulz, B. and Ziegel, J. (2026). Sequential model confidence sets. Journal of the Royal Statistical Society Series B: Statistical Methodology, qkag066. https://doi.org/10.1093/jrsssb/qkag066
Choe, Y. J. and Ramdas, A. (2024). Comparing Sequential Forecasters. Operations Research, 72(4), 1368–1387. https://doi.org/10.1287/opre.2021.0792
Howard, S. R., Ramdas, A., McAuliffe, J. and Sekhon, J. (2021). Time-uniform, nonparametric, nonasymptotic confidence sequences. The Annals of Statistics, 49(2), 1055–1080. https://doi.org/10.1214/20-AOS1991
Howard, S. R., Ramdas, A., McAuliffe, J. and Sekhon, J. (2020). Time-uniform Chernoff bounds via nonnegative supermartingales. Probability Surveys, 17, 257–317. https://doi.org/10.1214/18-PS321
Ramdas, A., Grünwald, P., Vovk, V. and Shafer, G. (2023). Game-theoretic statistics and safe anytime-valid inference. Statistical Science, 38(4), 576–601. https://doi.org/10.1214/23-STS894
Waudby-Smith, I., Arbour, D., Sinha, R., Kennedy, E. H. and Ramdas, A. (2024). Time-uniform central limit theory and asymptotic confidence sequences. The Annals of Statistics, 52(6), 2613–2640. https://doi.org/10.1214/24-AOS2408
Waudby-Smith, I., Ramdas, A. (2024). Estimating means of bounded random variables by betting. Journal of the Royal Statistical Society Series B: Statistical Methodology, 86(1), 1–27. https://doi.org/10.1093/jrsssb/qkad009